Cost Segregation
Cost segregation is a tax strategy that reclassifies components of a rental property into shorter depreciation schedules — 5, 7, or 15 years instead of the standard 27.5 — allowing short-term rental investors to front-load tax deductions, shrink taxable income in the early years of ownership, and redeploy the resulting tax savings into additional acquisitions or improvements.
Key Takeaways
- Cost segregation reclassifies property components from 27.5-year to 5, 7, or 15-year depreciation schedules, accelerating deductions
- Qualified engineering studies typically identify 20–40% of a property's cost basis for faster write-offs
- Combined with bonus depreciation, eligible assets can be fully deducted in the year of acquisition
- The strategy delivers its highest return for properties with a cost basis above $300,000 and owners in the 24%+ tax bracket
- STR hosts who establish material participation can apply resulting paper losses against W-2 and other active income — a benefit passive real estate investors cannot access
How Cost Segregation Works
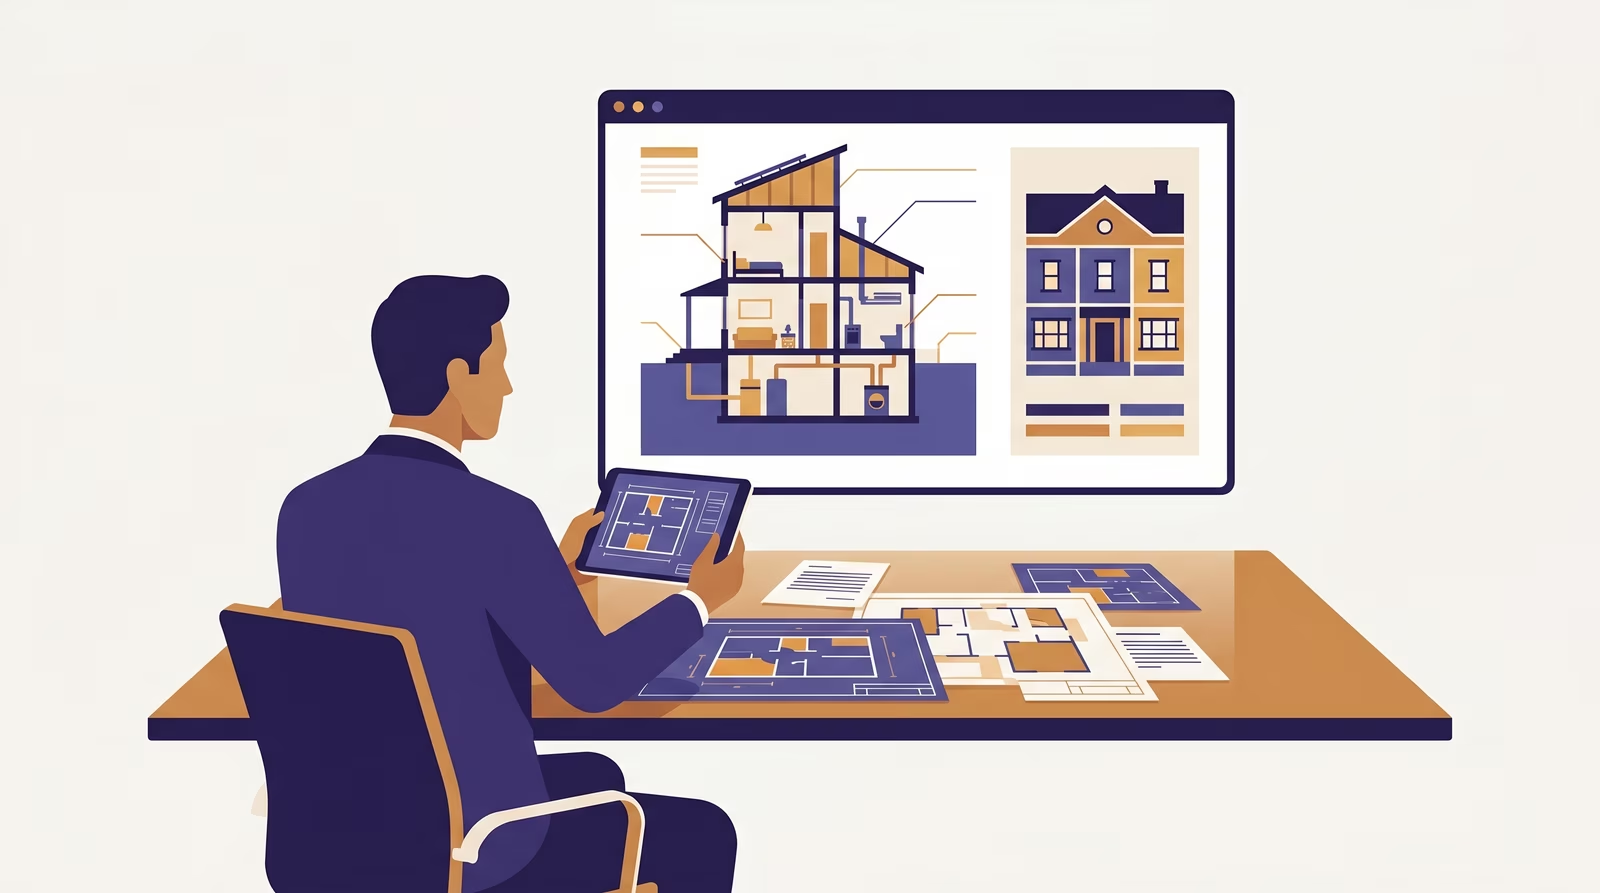
Standard residential rental depreciation allocates the entire depreciable building cost evenly across 27.5 years. A cost segregation study — conducted by engineers, not just accountants — performs a detailed physical inspection and component-by-component analysis to identify which assets qualify for accelerated schedules under the IRS Modified Accelerated Cost Recovery System (MACRS):
| Asset Category | Depreciation Period | Examples |
|---|---|---|
| Personal property | 5 years | Appliances, carpeting, furniture, decorative lighting, window treatments |
| Building components | 7 years | Specialized electrical, security systems, removable fixtures |
| Land improvements | 15 years | Landscaping, fencing, driveways, patios, outdoor lighting, sidewalks |
| Building structure | 27.5 years | Foundation, walls, roof, permanent HVAC, plumbing |
Tax Savings Illustration
| Scenario | Without Cost Segregation | With Cost Segregation |
|---|---|---|
| Property purchase price | $500,000 | $500,000 |
| Land value | $100,000 | $100,000 |
| Depreciable basis | $400,000 | $400,000 |
| Year 1 depreciation (straight-line) | $14,545 | $120,000+ |
| 5-year personal property identified (25%) | — | $100,000 |
| 15-year land improvements identified (10%) | — | $40,000 |
| Remaining 27.5-year structural basis | $400,000 | $260,000 |
| First-year tax savings (32% bracket) | $4,654 | $38,400+ |
With bonus depreciation available, the 5-year and 15-year components can be deducted in their entirety in year one, turning a moderate annual write-off into a six-figure first-year deduction.
The Material Participation Advantage for STR Hosts
The most powerful benefit of cost segregation in a short-term rental context depends on a single IRS classification: whether the rental activity is active or passive. Under IRS Publication 925, passive losses can only offset passive income — not salaries or business profits. However, STR hosts who qualify as materially participating can treat the rental as an active trade or business, allowing depreciation losses to offset any income source.
Material participation in a short-term rental requires spending more than 100 hours annually on the activity and more time than any other individual — a bar most hands-on hosts clear without difficulty. Once established, a $100,000+ depreciation deduction in year one becomes a direct offset to W-2 wages, potentially generating a five-figure tax refund.
For the STR host who is also a high-income earner, cost segregation effectively converts paper depreciation into a real, immediate cash benefit — the study pays for itself in the first tax filing.
This interaction distinguishes short-term rentals from long-term rentals under tax law. Long-term rental income is treated as passive by default under the passive activity loss rules, requiring a real estate professional designation (750+ hours) to unlock the same benefit. The STR exception is narrower and far more achievable for working investors.
Why Cost Segregation Works for Airbnb Hosts
- Front-loaded deductions: Accelerating depreciation matches cash-heavy early years — renovation, furnishing, setup — when owners need tax relief most
- Improved cash flow: Tax savings kept in-pocket compound when reinvested in property improvements, additional acquisitions, or ROI-improving amenities
- Scalability: Each new acquisition can receive its own study, compounding the tax benefit across a portfolio
- Works on existing properties: Look-back studies let owners capture missed accelerated depreciation on properties already held, with no need to amend prior-year returns
The strategy fits neatly into a broader investment stack. A host analyzing acquisition economics alongside DSCR loan financing should model cost segregation savings as part of the first-year cash position — the deductions can meaningfully change debt service math. Similarly, investors building a multi-property portfolio often pair cost segregation with a cash-flow focused market selection strategy.
When Cost Segregation Makes Sense
| Factor | Good Candidate | Poor Candidate |
|---|---|---|
| Property value | $300,000+ cost basis | Under $200,000 cost basis |
| Tax bracket | 24%+ marginal rate | 12% or lower |
| Holding period | 5+ years planned | Selling within 1–2 years |
| Participation | Material participation in STR | Passive investor only |
| Bonus depreciation | Available in current tax year | Fully phased out |
Bonus depreciation phasedown is a key timing consideration. Under the Tax Cuts and Jobs Act, 100% bonus depreciation expired after 2022 and steps down 20 percentage points per year. At 40% in 2025, a $100,000 pool of 5-year assets generates a $40,000 immediate deduction rather than $100,000 — still compelling, but shrinking. Completing a study before the next phasedown step locks in a higher deduction.
Pairing Cost Segregation with Other STR Tax Strategies
Cost segregation does not stand alone. Its full power emerges when combined with complementary strategies:
- 1031 exchange on exit: Deferring depreciation recapture through a 1031 exchange eliminates the 25% recapture tax on sale, preserving the full benefit of accelerated deductions taken during the hold
- Partial asset disposition: When replacing a major component — roof, HVAC, appliances — the undepreciated cost basis of the old component can be written off in the year of replacement
- Short-term rental tax election: For properties rented on average 7 days or fewer, income may qualify as self-employment income, changing the deductibility analysis
A deeper walkthrough of the full STR investment analysis framework is available in the STR investment analysis guide.
Frequently Asked Questions
Cost segregation is generally worth it for Airbnb properties valued at $300,000 or more with a cost basis (excluding land) of at least $200,000. The strategy works best for hosts with material participation status (100+ hours annually) who can use the accelerated depreciation to offset other income. For properties held less than 3 years or in low tax brackets, the benefits may not justify the study cost.
Yes, you can perform a cost segregation study on a property you already own through a 'look-back' study. The IRS allows you to catch up on missed accelerated depreciation in the current tax year without amending prior returns, using a Form 3115 change in accounting method. This means you can claim multiple years of additional depreciation deductions in a single year.
Bonus depreciation is an IRS provision that allows investors to immediately deduct a percentage of the cost of qualifying assets rather than spreading deductions over their depreciable life. Cost segregation identifies which property components qualify as 5-year or 15-year personal property, making them eligible for bonus depreciation. Under the Tax Cuts and Jobs Act, bonus depreciation was 100% through 2022, then stepped down 20% per year — at 40% in 2025 — so timing your study matters.
Depreciation recapture reduces but does not eliminate cost segregation's benefits. When you sell, the IRS taxes recaptured depreciation at 25% (Section 1250 unrecaptured gain). However, the time value of money means large upfront deductions are almost always worth more than deferred future taxes. Pairing a cost segregation sale with a 1031 exchange defers recapture entirely.